Showing posts with label clay carroll. Show all posts

Monday, October 1, 2018

Tips On Buying Your First Home

Buying your first home can seem pretty overwhelming at first. You search everywhere for the perfect location, saved your money and took the time to research. All that's left is to secure that mortgage! But how does the process start?

First, you will need a mortgage lender to issue you a mortgage pre-qualification form. From there the lender will ask you your gross (before tax) income is, what your monthly debts are (car payments, credit card minimums) and how much you have saved for your mortgage down payment and closing costs.

Remember, you are not looking to be approved quite yet just qualified.

The mortgage prequalification tells you that you should be able to afford a loan of X dollars and buy a home at X price. Although it is not an approval, it can save you a lot of time. One of the most important things mortgage pre-qualification tells you is what you can afford now. Pre-qualifications covers your income, assets, and debts. 

However, pre-qualification does not even involve a lender checking your credit or verifying your income.

Once you are prequalified for your home loan, the next step is easy. Complete a mortgage application with a local or online lender.

So do not be afraid to start the process of getting approved you can never be too prepared! Contact me today to begin the process!




Wednesday, October 11, 2017

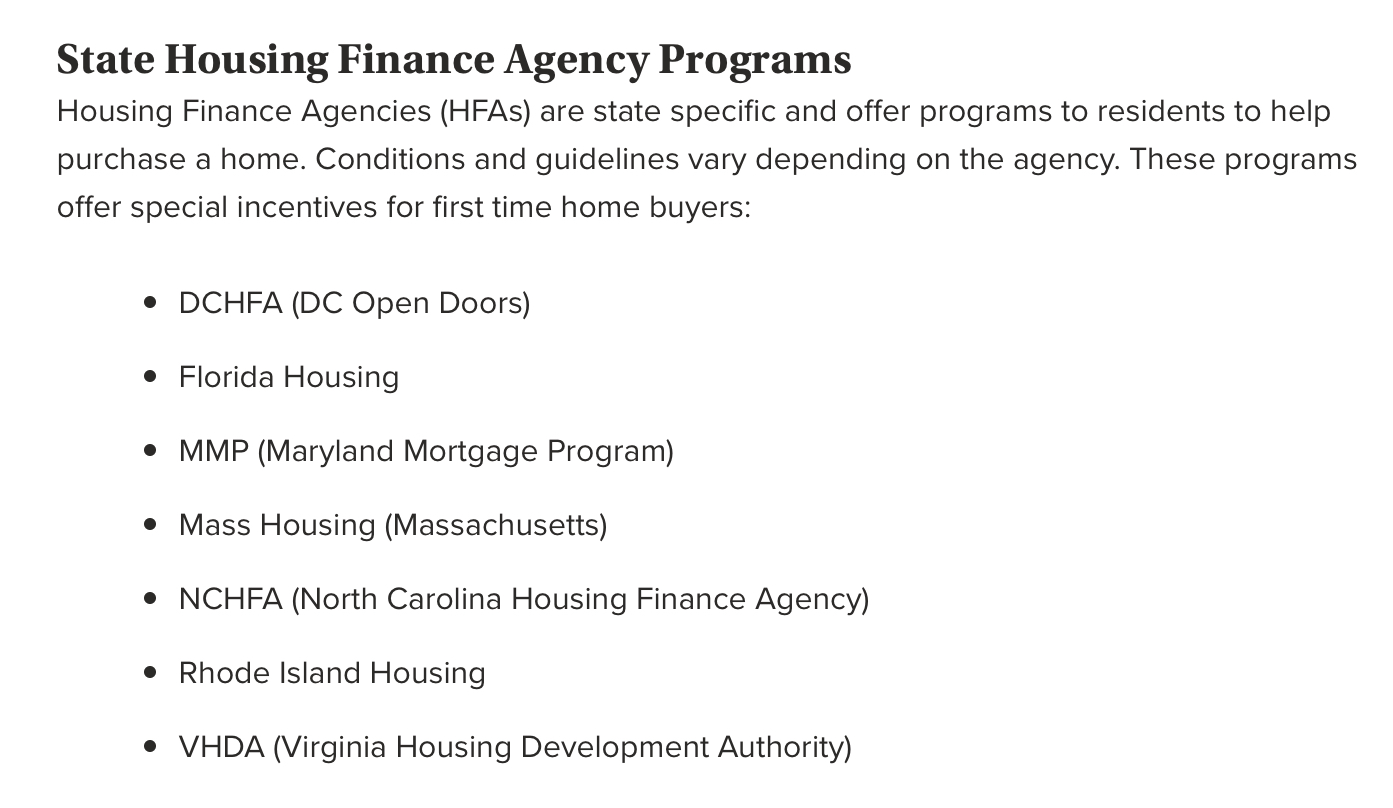
State Housing Finance Agency Programs


How can you make owning a home a reality? You know, a lot of people that I talk to everyday don’t realize that homeownership could be a reality for them. Why? Finances. Most people stress out about money and that they don’t have enough of it to buy a home. What’s so amazing about homeownership is that in some cases, your bills will stay about the same as if you were renting and in some cases, they may be lower! That’s pretty insane right? But it’s true, depending on what type of home you decide to purchase, your mortgage payment could be lower than your current rent. 

So how do we get you in a home without having a big downpayment? There’s quite a few State Housing Finance Agency programs which can help with not only the downpayment but with some of the closing costs too. Yes, you will have to bring some money to the table but it could be much lower than what you think! And if for whatever reason this isn’t an immediate goal for you, it’s important to meet with a Loan Officer to help you establish goals and checkpoints in order to get your finances in order and eventually become a homeowner. 

If you ever want to learn more information about what kind of assistance programs are available to you, make sure to give me a call! I’d love to speak with you about it. 

Monday, July 31, 2017

Pro's, and Con's, of Buying New Construction


If you’ve been shopping the Richmond Real Estate Market you’ve probably find yourself a little frustrated. There is a higher demand for housing than there are houses themselves. This is due to a number of things: there is a growing job market, people from surrouding metropolitan areas are moving to Richmond, the cost of living is reasonable and it is centrally located in Virginia. This makes Richmond an attractive place for people to move to. Fortunately, builders throughout Central Virginia have taken notice to this problem and they are proactively building to accomodate the housing demand. 

Pro’s

- It comes with a warranty so there won’t be a lot of out of pocket expenses if something breaks down
- No previous tenants, so you get a fresh start in a new home, everything will be brand new
- Most people in the neighborhood will be homeowners, at least for the first few years there won’t be a lot of rental properties
- In most cases you get to pick certain components of your home, such as: hardwood floors, additional bedrooms or bathrooms, finishes, etc. 

Con’s

- There is no way to see the finished home, the model home can provide an insight but not a definite design
- Sometimes your home might be finished before others, so you might have to deal with construction in your neighborhood
- There probably won’t be much room for negotiation
- Most houses will have a uniform look, at least on the outside, which depending who you ask may or not may be a good a good thing

This list doesn’t cover all the Pro’s and Con’s, but it does cover some of the most important ones. 

If you don’t know how to get started in the process of buying new construction, make sure to give me a call, because the very first thing you’ll want to do is get pre-approved. This way, you’ll know exactly which kind of new construction you can afford and you’ll be ready to make a purchase when the time comes. 

Friday, July 14, 2017

Grants Available for 1st Time Home Buyers in Virginia


VHDA is pleased to announce a special allocation of funding available to eligible first time homebuyers financing with either of VHDA’s Fannie Mae Programs.

Details
Assistance in the amount of $1500 provided towards the borrowers closing costs (including prepaids and upfront MI) – not toward downpayment

This is a grant – no deed of trust – no repayment required

Funding is limited – funding available for 150 purchases transactions – first come first serve

We anticipate funds will be utilized very quickly

Lower income limits – lower income limits apply (limits are lower than the VHDA grant program see attached limits)

Limited time – loans must close by October 17, 2017

Closing Costs assistance may be used in conjunction with VHDA’s DPA Grant and MCCs

Borrowers may not receive cash back at closing

Lenders may offer the closing costs assistance to borrowers currently locked with a VHDA Fannie Mae loan

- Chesterfield, Hanover, and Henrico income limit is $62,960, Richmond City is $62,960.

Thursday, June 29, 2017

Why Summer might be the best season to buy


We've all heard of a busy #Spring Real Estate Market. The Fall is another time in which Real Estate picks up. Winter tends to be too cold and people seem to be preoccupied with the Holidays. Summer might be a fantastic time for you to move into a new home because of the simple fact that the Spring frenzy has ended.

During the Spring season we see a lot of activity in the market, it can be harder to nail down moving plans because everyone has the same mentality at this point. Moving companies are getting lots of requests from people taking advantage of great weather. The market tends to be more competitive, more desirable homes might get several offers. That's added stress that you might not need. Real Estate Agents will have a bit more time in their hands now that the worst season is behind them, giving you the attention you deserve.

The Fall might be another season to consider if you're thinking of buying but historically we see some of the same issues we have during the Spring and if you experience any delays in the transaction you may end up having to move in the middle of Winter. This is why the Summer could be the perfect season to buy!

As always, if you have any questions on how the home buying process works, don't hesitate to give me a call!

Wednesday, June 7, 2017

Meet Your Builder!


Being in my industry right now is great. The housing market is better than it has been in many years. The economy and jobs have been making a steady comeback for the past few years and we're finally seeing some of those benefits. The only problem is that even though people are looking to buy homes, there isn't a ton of inventory out in the market. Why? Interest rates were high when people bought a number of years ago and people want to make sure they aren't losing money when they sell. It's a reasonable way of thinking but it puts potential buyers in a bit of a bind!

So as you can probably imagine builders are trying their best to provide more housing opportunities for buyers. There's lots of builders out there right now and getting to know them all can be overwhelming. Realtors should get familiar with all the different builders because it opens up a whole other market for their buyers.

Different builders have different: styles, quality, locations and square footage. Each builder brings something to the table that the next doesn't and it's important for lenders and realtors to get familiar with those differences. At the end of the day if we find the right home for our clients, we are successful at our job.

This is why I love being part of the Home Building Association of Richmond, there's so many great events that help connect Realtors, Builders and all sorts of Contractors. One of their biggest events is coming up soon, Builder Bash. The tickets for this event are sold out and it will take place at Bon Secours Washington Redskins Training Center on June 8th at 5pm. I suggest that you visit http://hbar.org/ to keep up with coming events if you'd like to get involved and get to know some really great people in the industry. I'm glad I joined!


Tuesday, May 23, 2017

Working with a Local Lender vs. Non-Local


Have you seen tons of ads online and on TV about mortgage rates and how low they are? Telling you that you can't get lower rates like that anywhere else? Yes, if you've been recently looking at houses it seems that these advertisements are everywhere and for good reason. Rates are not the lowest but they are pretty low compared to just a few years ago. The crazy thing is that the rates are mantaining even though the housing market seems to be booming.

The way to go might seem to use the "online tools" advertised or just do it with whichever bank you already have, it's so easy right?! Wrong. Getting a mortgage is not an easy process, at least not when you do it alone which is what it will feel like when don't work with a local agent. Having a real life person can make all the difference, especially when it is a local lender!

Options
Buying online should give you more options right? This is a big misconception mainly because there are some loans available to your state in particular that an online bank may not have access to or may not be very well versed in. It's impossible for an online representative to know every product available in every state and even if they are well educated in the subject, it's still impossible for them to know the ins and outs of every product. Being local gives us an advantage because of the products exclusive to your area and our experience dealing with them.

Flexibility
Don't qualify right away or need a little leeway with your mortgage? A local agent typically can be more forgiving and flexible on what we can offer based on your situation, in some cases even make exceptions. Big banks aren't really allowed to do this because they have strict guidelines to follow and even though we have guidelines too, it's easy for us to talk to our managers and get creative on how to help our clients. Our goals is to get you in your dream home!

We know the area
When you buy a mortgage online or even with the bank you usually do business with, it's not local therefore they don't have a full understanding of your needs. Knowing the area also helps because we can make sure you are getting a good deal and evaluation of the property. We'll know how much you'll need for the type of property you're looking to buy based on our extended knowledge of the area and prior loans.

Accessibility
When you use a big bank or an online option, you don't always get the same person on the phone or via email. Even if you do, they may not remember you because they work in such high volumes. Local lenders make it their priority to be a part of the process and keep you in the loop, we can even meet with you if you have questions! You can't this level of services when you don't shop local.

So when you're looking to buy, the first thing to do is shop for a mortgage with a local agent! Ask for references and check their presence online, make sure that they are good because this can make an experience that may seem complicated and intimidating into a pleasant one!


Tuesday, April 25, 2017

Golfing for a good cause: Special Olympics VA


I believe in giving back to the community and as my personal business grows, I want to make sure I am doing so. The Special Olympics is a great cause that I encourage people to get familiar with. We live in a very sport centered culture and I believe that everyone should be able to participate, the Special Olympics allows just that. We're not all the same and it is incredible to see an organization dedicated to embracing physical diversity.

This year, I decided to do a small part in making their Golfing Tournament a possibility. First Home Mortgage and myself are sponsoring one of the golf holes at this year's Golfing Tournament. I encourage friends and colleagues to register to play or support this cause by also becoming a hole sponsor. We all know someone with a disability and it is important to show them our support, no matter how big or small.

I hope to see some of you out there and if you're curious on how to get involved, click here to visit and get more tournament information or click here to learn more about the Special Olympics in VA.

Wednesday, March 15, 2017

Had a great talk about Financing!


Even though there was so many people without power yesterday, we had a pretty good turn out at the Salisbury Country Club for our Class "Top Financing Questions Every Realtor Needs to Know". This gave our Realtors 2 CE Credits.

We work very closely with our Realtors to make sure that they know how to answer financing questions when their clients ask. And yes, we don't expect them to know all the answers but that's why we offer these free classes for Realtors so they can have SOME answers.

Buying a home can be a scary process and talking about finances can be very personal for a lot, but in today's market it's more important than ever to have these conversations with our clients early on.

The most important thing to take away from our class is that even though rates remain low and the Real Estate Market remains healthy, we've seen a steady incline in rates, so if you've been thinking of buying, now is the best time to do so!

If you're too scared to ask, make sure that they contact us so we can clear up any questions that they may have, that's what we're here for!


Wednesday, February 1, 2017

No Matter The Loan, Big or Small, We Can Make Our Customers Homeowners


I want to take a moment to talk about one of my clients Zach, who was looking to buy a new home in the Richmond Area. Zach works in non-profit meaning that he works for a good cause but doesn't have a lot of disposable income. Having a restricted budget it was my job to figure out how to get him in a home that he would be happy with and that wouldn't strain him too much financially. 

Even though he didn't have a large budget, he also wanted to buy something that was move in ready and that didn't need a lot of renovations - with the help of Kristina Davis Denzler from Clocktower Realty, we are able to find something that checked off all of Zach's needs and wants. 

His monthly payment is something that he can easily handle, just under $1,000 a month. It's close to the city, just a few minutes away and with enough room to entertain and have people over. 

Having the RIGHT Realtor and the RIGHT Lender can really make all the difference. I want to make a difference when it comes to your Real Estate needs. If you want to find out more of what I can do for you and your family, please give me a call! Spring is just around the corner and it would be really great if can get you into a new home then! 


Wednesday, January 11, 2017

Member of the Richmond Mortgage Banker's Association


I have some very exciting news to share with all of you. I have become a Board Member of the Richmond Mortgage Banker's Association (RMBA). What better way to help all of my clients than by being part of this amazing group of people who directly influence the Mortgage Industry in Virginia.

So who is the RMBA? They are the people who research the Richmond Mortgage Industry and figure out what needs to be done to it. Then they communicate their findings to the Virginia Mortgage Lender's Association (VMLA), which lobbies and molds legislation so it can protect and benefit our clients' interests. The RMBA is composed of people from all over the Mortgage Industry in #RVA. My goal is always to make it as easy and painless for my clients to be home owners, and getting involved with the RMBA is just another way to make this happen. Homeownership is after all the American dream.

The RMBA also holds regular educational events geared towards loan officers, this is great for me because it provides direct access to tremendous amount of information that benefits my customers.

I am excited to be a part of this organization in 2017 and I can't wait to see what other amazing things come my way!


Saturday, November 19, 2016

Welcome to our team!


Jessica has joined the Clay Carroll First Home Mortgage team this week and I couldn't be more excited to have her on board! Her experience alone is invaluable but she is also an excellent people person.

Jessica, a native of Richmond VA, has been in the real estate business for nearly 20 years.  Starting her career just after high school, Jessica relocated to San Diego, CA where she lived for two years and spent another 5 years in Dallas, TX working in the real estate closing industry.  Although, she loved Texas, her heart was home in King William County where she moved in 2014 and married her husband in 2015.  Jessica understands that customer service should be expected and strives to go above and beyond in effort to create raving fans.  Her wealth of knowledge in all aspects of the Real Estate/Mortgage Industry helps her stay ahead of the curve in the ever changing market.  In addition,  Jessica brings outstanding communication skills, a get it done attitude, and contagious smile to First Home Mortgage and is also a big part of helping us create a mortgage experience to the customer that is second to NONE.

In her spare time she also enjoys watching sports, hunting with her husband, and spending time with her family.

Tuesday, November 15, 2016

Hear what people are saying...


Great Experience with Clay

We had a great first time home buying experience with Clay. Clay made sure that everything went as planned and my wife and I now live in the home of our dreams.
LOAN STATUSClosed Jul 2016
LOAN TYPEConstruction
CLOSE ON TIMEYes

Great Job!

Clay did an AMAZING job in our home purchase. Two BIG thumbs up!! We were looking for a specific home, and came through with shining colors. Process was easy, and he was in full communication the whole time! 
LOAN STATUSClosed Jul 2016
LOAN TYPEPurchase
CLOSE ON TIMEYes

As a first time homebuyer I was nervous and worried but Clay put all my mind to ...

Clay helped us from start to finish leaving no question unanswered. A truly hassle free experience in getting our mortgage!! As a first time homebuyer I was nervous and worried but Clay put all my mind to rest! I would highly recommend he and his team to help you purchase/refinance your home!
LOAN STATUSClosed Apr 2016
LOAN TYPEPurchase
  • In today's challenging and demanding market, he dealt with my frustrations ...

    Clay followed through with everything he promised. In today's challenging and demanding market, he dealt with my frustrations in a calm composed manner. He answered every question I asked and completed the process as painlessly as possible.
    LOAN STATUSClosed Apr 2016
    LOAN TYPEPurchase

    He always had time for us regardless if we needed something on the weekend or past ...

    Clay is very informative, able to answer all of our questions and address any and all concerns immediately. He always had time for us regardless if we needed something on the weekend or past 'normal' working hours. We already have recommended Clay and his team, and will continue to do so in the future.
    LOAN STATUSClosed Apr 2016
    LOAN TYPEPurchase

Thursday, November 10, 2016

Loan Options


Loan Options

As a home buyer, your mortgage is specific to your situation and lifestyle. First Home Mortgage specializes in a variety of loans that can meet your needs. Your Loan Officer will explain your options and deliver a mortgage with the best loan terms available.

PURCHASE AND REFINANCING LOANS

Conventional Home Loans

Conventional mortgages are loans that are insured by private companies. Typically, these loans meet the funding criteria set by Fannie Mae and Freddie Mac. There are a number of conventional loan types offered by First Home Mortgage:

FIXED RATE

A fixed-rate mortgage has an interest rate that stays the same for the entire life of your loan. This offers a predictable monthly payment for a term of 10 – 30 years.
Highlights
– Interest rate security
– Monthly payment stability
– Best for buyers planning to stay in their homes for a long time

ADJUSTABLE RATE

Adjustable rate mortgages (ARMs) may allow you to lock in a low, introductory interest rate that could increase over time. A hybrid ARM offers a fixed period (typically 3-10 years) followed by a yearly adjustment to the interest rate. Hybrid ARMs are often represented by fractions, such as 5/1 – meaning the first rate reset takes place after five years and continues to reset each year for the life of the loan.
Highlights
– Low starting interest rate
– Lower monthly payments during the initial term
– Best for buyers planning to keep their loan for a shorter period

JUMBO

Jumbo loans typically have higher loan amounts not allowed for standard conforming programs (set by Fannie Mae and Freddie Mac). This allows borrowers to a purchase a higher priced home with an affordable down payment.
Highlights
– Fixed and ARM options
– Loans up to $3 Million
– Best for borrowers who are in the market for higher priced homes

Government Loans

The government guarantees certain programs through various agencies to better serve borrowers with unique circumstances. These loans can only be offered through an approved lender such as First Home Mortgage.

FHA

FHA loans are insured by the Federal Housing Administration (FHA). Programs are available for borrowers with limited savings for a down payment.
Highlights
– Down payment as low as 3.5%
– Flexible use of gifts and grants for down payment
– Best for borrowers with limited assets for purchase

VA

VA loans are insured by The Department of Veterans Affairs (VA).Service members and their spouses are eligible to purchase with little to no down payment or cash to close.
Highlights
– Low to no down payment
– Refinance within the VA program without re-qualifying
– Specifically for eligible past and present service members and spouses

USDA

The U.S. Department of Agriculture (USDA) insures loans to home buyers with low to moderate income moving to designated rural areas. These loans can provide up to 100% financing.
Highlights
– Down payment not required
– Specific benefit needed here
– Best for borrowers with limited assets looking to buy in rural areas

State Housing Finance Agency Programs

Housing Finance Agencies (HFAs) are state specific and offer programs to residents to help purchase a home. Conditions and guidelines vary depending on the agency. These programs offer special incentives for first time home buyers:
  • VHDA (Virginia Housing Development Authority)

Friday, November 4, 2016

Applying for a Loan


Pre-Qualification

The first step toward a home purchase is getting pre-qualified for a loan. Your Loan Officer will review your financial information and determine how much you are qualified to borrow. As a pre-qualified buyer, your offer on a home is more likely to be accepted.
  • Loan Preparation Checklist
    1. Copy of photo ID
    2. Social Security number
    3. Copies of checking and savings account statements for the past 3 months
    4. Most recent pay stubs detailing your year-to-date earnings
    5. Federal tax returns with W-2’s, K-1’s, 1099 for the past 2 years
    6. Evidence of any other assets such as stocks and bonds
    7. Contact name and address of someone who can verify your employment
  • Since everyone’s situation is unique, additional documentation might be required. Your Loan Officer will let you know exactly what is needed.

Making an Offer

Once you have found a home, you will make an offer to buy it from the seller. A real estate professional will conduct negotiations and a contract will be submitted to purchase, accompanied by the pre-qualification letter.

Mortgage Process

When the seller accepts your offer, you begin the mortgage process. Your Loan Officer will gather your financial information, loan application and provide the initial disclosures based on your loan terms.
  • This process will also include
    1. Ordering the appraisal; estimating the value of the home
    2. Ordering/updating your credit report
    3. Submitting your loan to Underwriting for review
    4. Conditionally approving your loan (additional documentation might be requested)
    5. Providing information on homeowner’s insurance and selected title company
    6.  Underwriting approval on all acceptable documents
    7. Final loan approval – you are cleared to close!
  • Your Loan Officer will keep you informed, answer your questions, and navigate you through the loan process.

Closing Process

In the days leading up to settlement, you will be sent final documentation about your loan, including the Closing Disclosure. You must review, sign and return the paperwork a minimum of three days prior to your scheduled closing date.
Your Loan Officer, or a designated employee, will tell you the amount of money you need to close on your home.
  • What happens on closing day
    1. Meet with your settlement agent as well as your Loan Officer, or designated employee.
    2. Provide funds to the title company to cover your down payment, closing costs, taxes, insurance and other costs.
    3. You and the seller will execute all closing documents so the settlement agent can properly record the purchase of your home.

Making Your Payment

Your settlement documents will include instructions on how to make your first payment. While First Home services many of our loans, it is possible servicing will be transferred. You will be mailed a notification that designates your mortgage servicer.

Thursday, November 3, 2016

I do both Construction & Renovation Loans!

Renovation and Construction

RENOVATION

A renovation loan can help fund home improvements, allowing you to turn a house into your dream home.

Renovating for a new home purchase

If you’re a buyer who’s found a home with great potential, but needs some repairs, First Home can provide a loan for the purchase and renovation costs. We offer a number of loan types that cover minor to major rehabilitation, all included with one mortgage payment.

Improving your current home

If you’re a current homeowner who’s interested in making updates that would enhance the look and layout of your house, a renovation might be the solution. Based on the type and scope of your remodel, we can offer a variety of loans that will help with the cost.
Types of repairs and remodels include:
  • Room addition
  • Garage, driveways
  • Roof & gutters
  • Plumbing & electrical
  • Decks, patios, porches
  • Basement finishing
  • Doors, windows
  • Landscape, fencing
For a full list of eligible improvements and considerations, contact a First Home Mortgage Loan Officer.

CONSTRUCTION

Building a Home

Breaking ground and watching your custom home take shape is possible with a construction loan from First Home Mortgage. You have the option to apply for a loan that covers construction only, or a loan that finances the construction and later transfers to a standard mortgage.
Talk to us about what you envision for your new home, we’ll help you make it happen.

Monday, October 31, 2016

Show me your best Pumpkin Carving Skills!

So every year, I drop off pumpkins to a handful of clients and partners and I hold a contest to see who can do their best. It's an awesome contest that gets the family involved and it's just a great activity to do around this time of year. Check out the entries we've received so far! More to come...


Thursday, October 27, 2016

Can refinancing save you money?!


Refinancing

Refinancing is a possibility to improve your current mortgage. It means getting a new loan, with new terms, and using that money to pay off your old loan. Your Loan Officer can help explain why refinancing might be the right option for you.

Reasons to Refinance


  • Lower payments
    Refinancing with a lower interest rate could result in lower mortgage payments. This may provide extra money each month for homeowners to save, or spend, however they choose.
  • Shorten your payment term
    If you want to build equity faster, or pay off your mortgage in less time, you can refinance to a shorter loan term. This may result in a slightly higher monthly payment, but you may also save money by paying less toward interest.
  • Convert your home’s equity into cash
    As a homeowner, you make payments to increase your equity, or value of ownership. Refinancing allows you to turn that equity into cash – referred to as “cash-out” refinancing. You are free to access and spend the money without tax penalty*.
    *Consult a tax professional for more information.

Tuesday, October 25, 2016

Ask yourself the following questions when buying a home


Questions to consider as a home buyer:

How much can I afford?
Before you starting house hunting, you need to make sure you are looking in the right price range. Getting pre-qualified by your Loan Officer will give you a better idea of how much home you can afford based on your current financial situation.
How long do I want to stay in my home?
Think about where you will be in the years to come; whether you want to move again or planning to stay long term. This is an important factor when deciding which type of mortgage is best for you.
What am I looking for in a home?
As you begin to contemplate buying, make a list of the most important things you want in a home. For example: a condo or single family home, monthly mortgage payment, location to work and school zones, neighborhood amenities, and yard size. Not only will this list help your real estate professional find the perfect home, it will also help your Loan Officer tailor a loan program that fits your needs.
Should I consider a second home?
Buying another property as a rental can provide ongoing income from tenants, and a vacation home on the beach or mountains is equally attractive. However, you will need to decide whether the home will be a place to live (primary residence) or a place to rent (investment property). Loan specifications are different based on how you plan to utilize the home. Your Loan Officer can explain the different requirements and help navigate through the process.

Sunday, October 23, 2016

Thinking of buying? Here's some benefits of Homeownership!


Benefits of homeownership:


  • Build Wealth  Although home value may increase or decrease short term, if you decide to stay in your home long term, it could gradually increase in value. This would provide you with a significant return on your investment.
  • Build Equity  Equity is the amount of money your house is worth minus what you still owe. Every time you make a mortgage payment, the amount you owe reduces and increases overall equity. This is beneficial, because equity can be accessed and converted to cash. See our Refinancingpage to learn more.
  • Tax Deductions  As a home owner, your mortgage interest and property tax payments may be deductible from your federal taxes and possibly state taxes.*
    *Consult a tax professional for more information.
  • Strengthen Credit History  Making monthly loan payments is evidence that you are a responsible borrower, which builds your credit history. This will help you take out loans for other purchases, such as a car or even home renovations.
  • Create the Home You Want  Owning a home gives you the freedom to create your dream living environment. Whether you want to update appliances, paint rooms, landscape a yard, own pets – you will have a house that is completely yours to customize.